Construction insurance after QBE’s exit in France : prove it or pay
Why has construction insurance become so expensive, and so hard to obtain, for building contractors? QBE's exit from French decennial liability insurance, confirmed on 2 September 2026, exposes a model under strain. Insurers are losing money, contractors are paying more, and the uncertainty that makes a risk insurable is fading. At Certificall, we believe part of the answer lies on the construction site itself: in the quality of the evidence.
Key takeaways in 30 seconds
- In 2024, French construction insurance collected €3,177m in premiums but posted a technical result of −€827m, its worst on record (France Assureurs).
- QBE is terminating its entire French decennial liability portfolio on 1 January 2027: capacity is concentrating and underwriting is tightening.
- Under the presumption of liability in Article 1792 of the French Civil Code, the contractor's insurer is almost certain to pay.
- Certificall lets construction companies prove that each key stage was properly executed, with certified, time-stamped and geolocated photos and videos.
Construction insurance in France: a loss-making market despite record premiums
French construction insurance rests on two compulsory covers created by the Spinetta Act of 4 January 1978. Decennial liability insurance (RCD) covers the contractor for ten years after handover (Article L. 241-1 of the French Insurance Code). Building damage insurance, known as dommages-ouvrage, pre-finances repairs for the owner without waiting for liability to be established (Article L. 242-1).
€3,177m
Premiums in 2024
Highest level since 1983, up 3.5% (France Assureurs).
74%
Share of decennial liability
Decennial liability accounts for most of the line's premiums.
−€827m
Technical result in 2024
The worst level ever recorded by the construction line.
67%
Water-tightness defects
Between 2023 and 2025, up from 61% in the previous edition (AQC, 2026).
That is the paradox: premiums rise while results collapse. Sarah Sehli, head of construction insurance at the wholesale broker Add Value, points to several factors (News Assurances Pro, 9 June 2026). She cites persistent claims, rising repair costs, the building recession and climate risks. Fewer housing starts also shrink the premium base.
The 2026 Construction Quality Observatory of the Agence qualité construction (AQC) shows the nature of the problem. Water-tightness defects dominate, far ahead of structural failures (11%). These are frequency claims, often linked to workmanship: exactly the defects that well-documented site monitoring can prevent or explain.
QBE's exit: the symptom of a decennial risk that no longer pays
Present in France since 1997, QBE covered a broad range of risks, from sole traders to mid-sized firms, including solar PV and anaerobic digestion. It had already scaled back cover for tradespeople with a turnover below €500,000. On 2 September 2026, QBE France confirmed its exit: its whole decennial liability portfolio will be terminated on 1 January 2027. Works carried out while the policies were in force remain covered.
Sarah Sehli sees it as "a strong signal of capacity concentration" (translated from French). Decennial cover for small firms now relies on a handful of mutuals, generalists and niche specialists. Small contractors face steep price increases, or a refusal that sends them to the Bureau central de tarification (BCT), France's central pricing bureau. In the medium term, she fears a de facto oligopoly.
Loïc Toth, General manager and partnar at a broker specialising in commercial insurance, especially in the construction sector, goes further in a LinkedIn post about QBE. In his view, "an insurer does not leave a line of business if its loss ratio is profitable" (translated from French). He expects rejected contractors to turn to fragile insurers in 2027, and fake insurance certificates to multiply.
New capacity is emerging. On 24 August 2026, APRIL Construction partnered with Fidelidade France to underwrite, from 1 January 2027, policies left exposed by departing insurers. The market is not closing: it is becoming more selective, more expensive and more demanding about the quality of submissions.
The presumption of liability: the mechanism that removes uncertainty
The presumption of liability is the rule set by Article 1792 of the French Civil Code. For ten years after handover, the contractor is strictly liable for damage that affects the soundness of the building or makes it unfit for use.
The owner does not have to prove fault. The contractor can only escape liability by proving an external cause (Article 1792, paragraph 2): force majeure, the act of a third party or of the owner. Doing good work is not enough.
The claims process reinforces this mechanism. The building damage insurer must state its position within 60 days and make an offer within 90 days (Article L. 242-1 of the French Insurance Code). It then recovers from the contractors and their liability insurers, often under the CRAC agreement that organises these recoveries between insurers.
The same broker estimates that in 90% of cases, contractors fail to rebut the presumption. This is a practitioner's estimate, not a published statistic. It reflects a reality: the liability insurer often pays without going to court, for lack of arguments. Solar PV is a case in point: at the slightest claim, the installation is blamed and the presumption ends the debate.
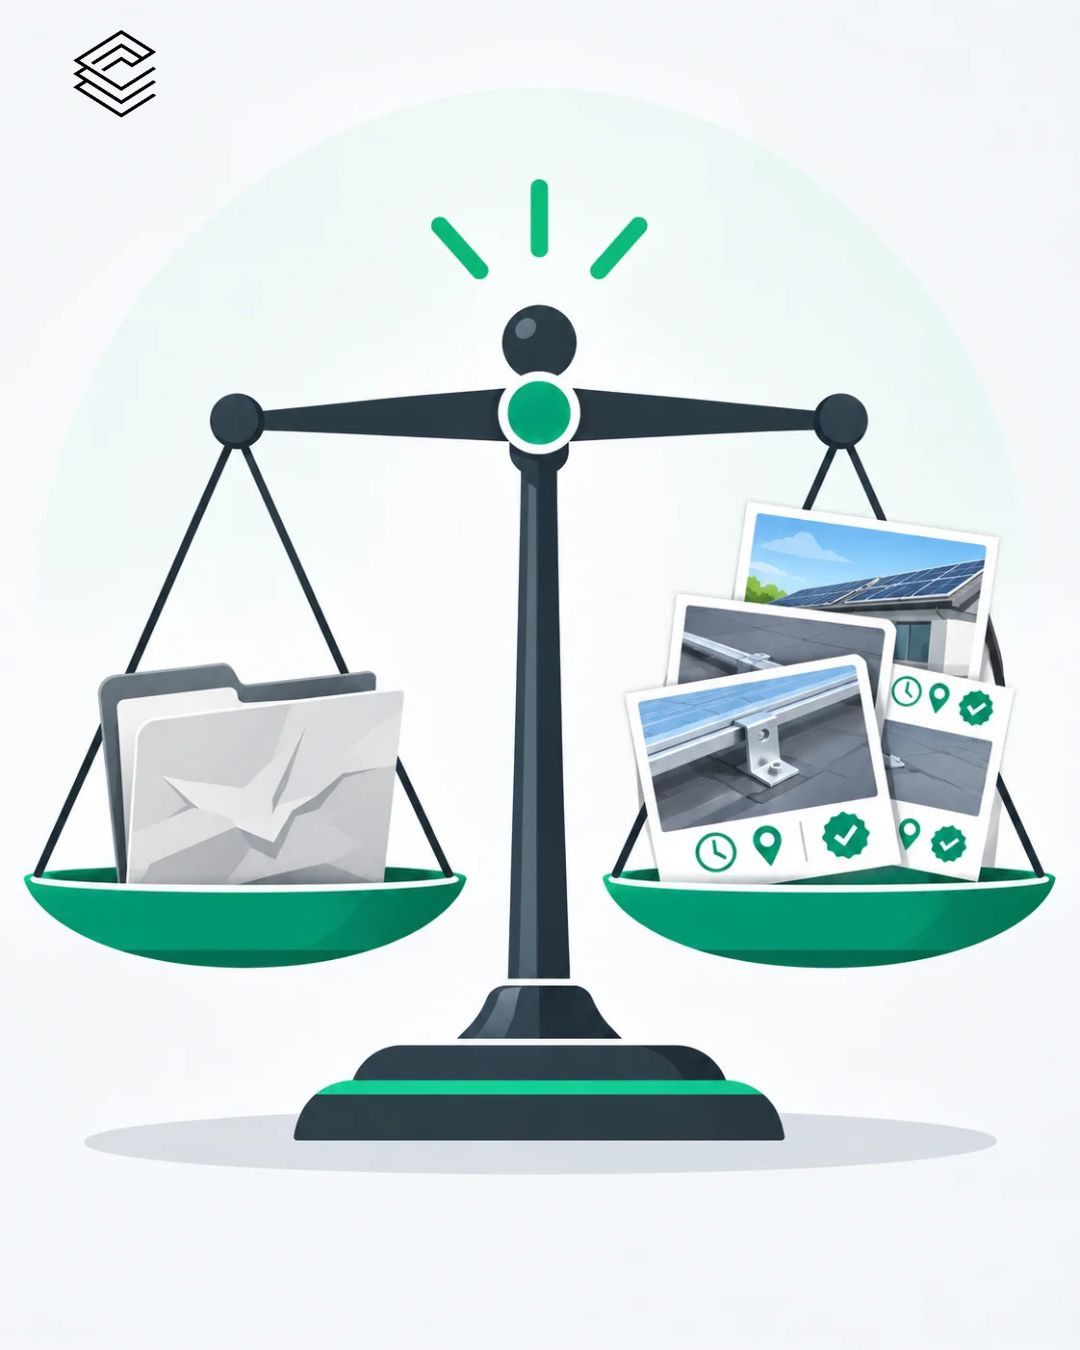
When payment becomes certain
Insurance relies on uncertainty: when the contractor's insurer is almost sure to pay, it no longer pools a risk, it pre-finances an expense.
For construction companies, three effects follow:
- Premiums: they track expected claims, not a probability.
- Deductibles and limits: the insured takes back a growing share of the risk.
- Access: refusals, multi-year commitments or referral to the BCT for profiles deemed too exposed.
Construction defect claims: who really pays the bill?
When insurers can no longer spread the risk, they hand it back to their policyholders. Contractors see it at every renewal.
| Party | What it faces | Consequence |
|---|---|---|
| Liability insurer | Near-certain claims, hard recoveries from insolvent contractors | Tighter selection, price rises, market exit |
| Contractor | Higher premiums, deductibles and documentation demands | Lower margins, risk of losing cover |
| Owner | Long surveys, litigation, uninsured contractors | Delayed compensation, fake certificates |
Rising litigation makes the spiral worse. Disputes focus on how defects are classified, who caused them and what repairs cost. Some proceedings mainly seek damages. Every poorly documented file is settled at the expense of reliable contractors, who end up paying for everyone's claims. And without a valid decennial certificate, a contractor can no longer bid for most projects.
What site evidence changes in a decennial claim, and what it does not
Let us be precise: a certified photo does not overturn the presumption in Article 1792. It does, however, carry weight on the points that decide the outcome of a file.
| Disputed point | Question raised | What certified evidence brings |
|---|---|---|
| Visible defect | Was the defect visible at handover (Article 1792-6)? | Condition at handover, dated snags and snag clearance |
| Attribution | Does the damage fall within the contractor's package? | Condition at the end of the package, before other trades |
| External cause | Is a third party or poor maintenance involved? | Dated photos of later works and damage |
| Recovery between parties | How should the final cost be shared? | Traceability of stages and self-inspections |
| Severity and cost | Is the defect really decennial? What does the repair cost? | An objective basis for the joint expert survey |
The evidence still has to hold up. An ordinary photo is easy to challenge: editable date, uncertain location, retouched image. That is why a photo alone proves nothing unless the way it was captured can be trusted. A Certificall photo carries a qualified time stamp under the eIDAS Regulation (EU) No 910/2014 and a geolocation. A qualified electronic seal locks the file. Certificall therefore complements, but does not replace, a bailiff's report in the heaviest litigation.
Illustrative scenario: a leak under a solar PV array
This case is fictitious. A small firm installs a rooftop solar array on a warehouse. Eighteen months after handover, a leak appears. The building damage insurer compensates the owner, then turns to the installer and its liability insurer.
Without evidence, the outcome is settled in advance. With a certified file, the company shows the roof before installation, the fixings and the waterproofing joints, then the finished works at handover. The photos also reveal that another contractor drilled through the roof six months after handover. The discussion then turns to attribution and external cause.
Insurers and brokers: managing the loss ratio through site evidence
The loss ratio compares the claims cost of a portfolio with the premiums earned: above 100%, the insurer pays out more than it collects.
Construction insurers know which defects recur, on which buildings and at which stage. They also know which documents were missing from the files they lost. This field knowledge is the raw material of prevention.
With Certificall, an insurer or broker can ask policyholders for certified evidence at high-risk stages: waterproofing before covering, fixings, networks, handover. The result is stronger recoveries and faster claims handling. At underwriting, this evidence feeds a sharper risk score from the very first field visit. Our insurance offer is presented on the certified photo for insurance page.
Certificall integrates with existing tools through its API and SDK. We work with building experts and technical bodies to define the inspection points that matter. We invite construction insurers and brokers to join us: your view of claims helps target the evidence that actually prevents defects.
Insurers, brokers: let's build the evidence protocols that will bring your loss ratio down
Share your reading of claims, we turn it into certified inspection points.
The insurance submission: a new evidence culture for contractors
Insurers now favour well-organised companies: proven techniques, verifiable references, documented claims history, demonstrable prevention. A contractor who documents its sites arrives at renewal with facts. Its submission becomes a pricing argument. Roofers, waterproofers, window fitters, solar installers and heavy renovation firms are first in line.
6 pieces of evidence to build on every site
- Initial condition. Substrate, existing structures and neighbouring properties before works.
- Hidden stages. Waterproofing, fixings, networks and insulation before covering.
- Self-inspections. Dated checkpoints against the applicable technical standards.
- End of package. Condition of the works before other trades arrive.
- Handover. Handover report, photos of snags, then of their clearance with a punch list app.
- After handover. Third-party works and lack of maintenance.
With the Certificall app, every team member always has an evidence tool in their pocket. Each shot becomes construction photo evidence, filed by project and shareable with the client or insurer. The qualified time stamp fixes the date of each stage. Site managers can also inspect a site visually without travelling. Our certified photos for construction page explains how to prove compliance from initial condition to handover.
Construction insurance in Europe: different regimes, the same need for evidence
Several European countries have adopted an obligation close to French decennial liability. Others rely on contractual warranties.
| Country | Regime | Key point |
|---|---|---|
| Belgium | Act of 31 May 2017 (Peeters-Borsus), in force since 1 July 2018 | Compulsory decennial liability insurance for contractors and architects on residential works |
| Spain | Building Act 38/1999 (LOE) | Seguro decenal compulsory since 6 May 2000 for residential buildings, taken out by the developer |
| Italy | Legislative Decree 122/2005 and Ministerial Decree 154/2022 | Polizza decennale postuma compulsory for homes sold off-plan |
| United Kingdom | No statutory decennial insurance | 10-year structural warranties required by lenders; limitation period extended to 15 years by the Building Safety Act 2022 |
| Germany | No compulsory insurance | 5-year statutory warranty for building works (Section 634a BGB) |
Everywhere, rising repair costs are pushing claims up. Everywhere, too, proving what was done, when and where, decides the outcome of claims. The eIDAS Regulation applies in all 27 EU Member States. A qualified time stamp enjoys a presumption of accuracy of the date and integrity of the data (Article 41). Certificall can therefore support contractors and insurers across Europe.
Certificall: proving good workmanship to stay insurable
Certificall is a French digital evidence certification platform for documenting construction sites, from initial condition to snag clearance. More than 3,000,000 certifications have already been carried out with Certificall. Data is hosted in France, in line with the GDPR. Certificall's certification technology combines a qualified time stamp, geolocation and a qualified electronic seal. Its proprietary AI, developed in-house, detects manipulation such as photos of photos, a challenge shared by all capture tools.
The construction insurance market will not go back. Companies that prove their work will remain insurable on sustainable terms. Insurers that require this evidence will improve their technical results, and owners will be compensated faster.
Contact us to integrate Certificall into your business processes
Document every stage of your sites and approach your insurance renewal with a solid file.
The questions we are really asked about construction insurance
- ❓ What is the presumption of liability in French construction law?
- It is the rule in Article 1792 of the French Civil Code: the contractor is strictly liable for decennial damage for ten years after handover. The owner does not have to prove fault. The contractor can only escape liability by proving an external cause.
- ❓ Why is QBE leaving decennial liability insurance in France?
- QBE France confirmed on 2 September 2026 that it is ending its decennial liability business, as part of a refocusing. The exit comes as the construction line posted a technical result of −€827m in 2024, according to France Assureurs.
- ❓ What happens to projects insured by QBE after 1 January 2027?
- Works carried out while the policy was in force remain covered until the end of the ten-year period. Sites opened from 1 January 2027 must be covered by a new insurer, which contractors should arrange early with their broker.
- ❓ What can a French contractor do if decennial insurance is refused?
- It can refer the case to the Bureau central de tarification (Article L. 243-4 of the French Insurance Code). The BCT sets the premium at which the insurer approached must cover the risk. A well-documented submission remains the best way to avoid a refusal.
- ❓ Can a certified photo release a contractor from decennial liability?
- Not on its own: good workmanship does not overturn the presumption in Article 1792. A certified photo carries weight on attribution, on whether the defect was visible at handover, on external cause and on how costs are shared.
- ❓ How can an insurer reduce the loss ratio of a construction portfolio?
- By reducing defect frequency and strengthening recoveries. Requiring certified evidence at high-risk stages improves risk selection, on-site prevention and claims handling.
- ❓ Does construction insurance work the same way elsewhere in Europe?
- No. Belgium, Spain and Italy impose a form of decennial insurance, while the United Kingdom and Germany do not. Everywhere, evidence of workmanship decides the outcome of claims.